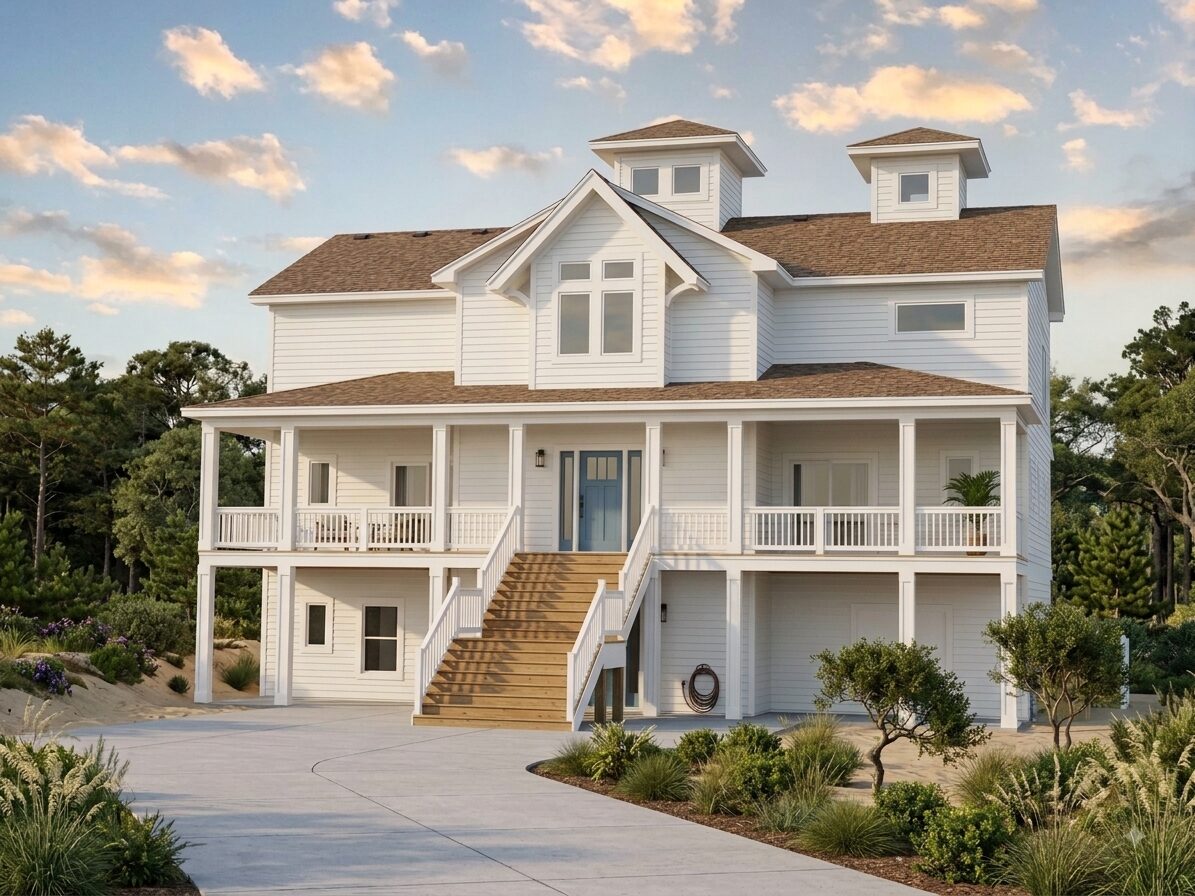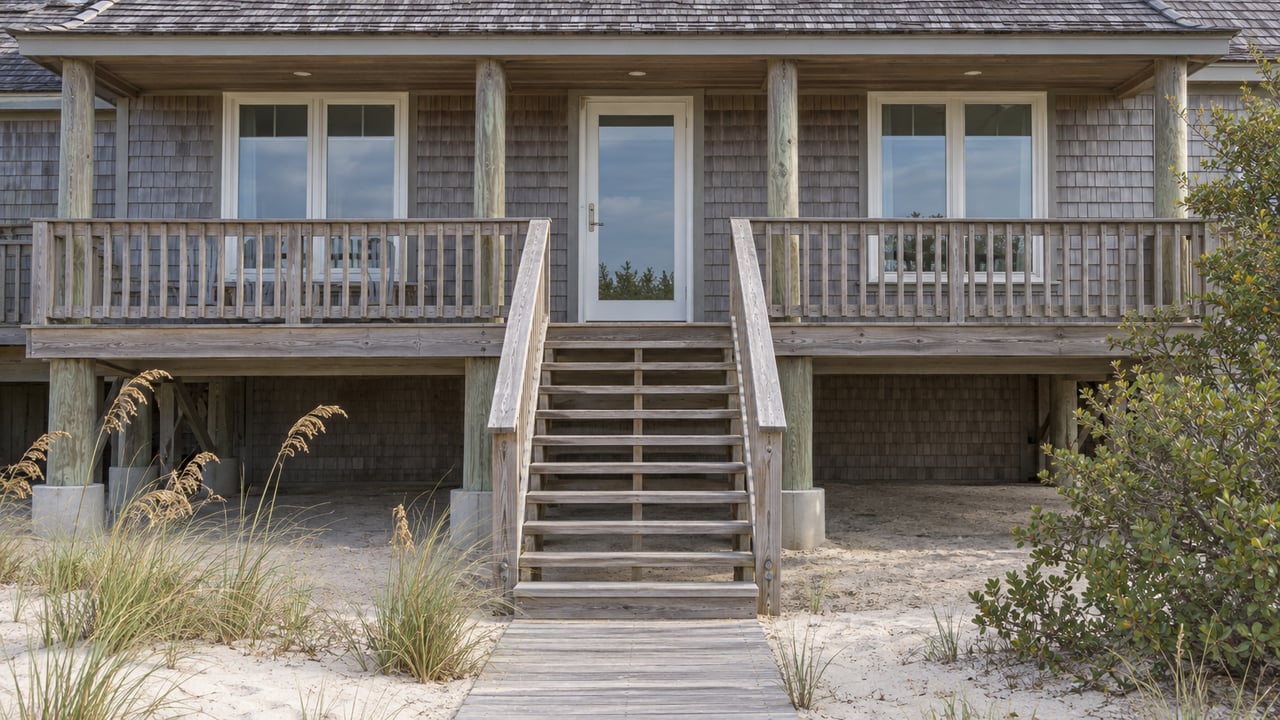
A buyer we'll call typical falls for an oceanfront listing in Corolla, puts in an offer, and calls a lender to lock financing. The lender comes back with a problem that has nothing to do with the buyer's credit or the price of the house. The address sits inside a federally designated Coastal Barrier Resources System unit, which means any structure built there after 1982 cannot carry a National Flood Insurance Program policy. No NFIP coverage means no conventional loan, no FHA, no VA, no USDA. The buyer pool for that house is cash and a handful of portfolio lenders willing to write against private flood coverage.
That house is in Corolla. So is a three-bedroom condo with a trolley service to the beach and a heated pool. So is a cottage with a well and a septic tank on a soundside lot. The word "Corolla" is doing far more work than most buyers realize, and understanding why matters more than any single price you'll see quoted.
One Post Office, Not One Town
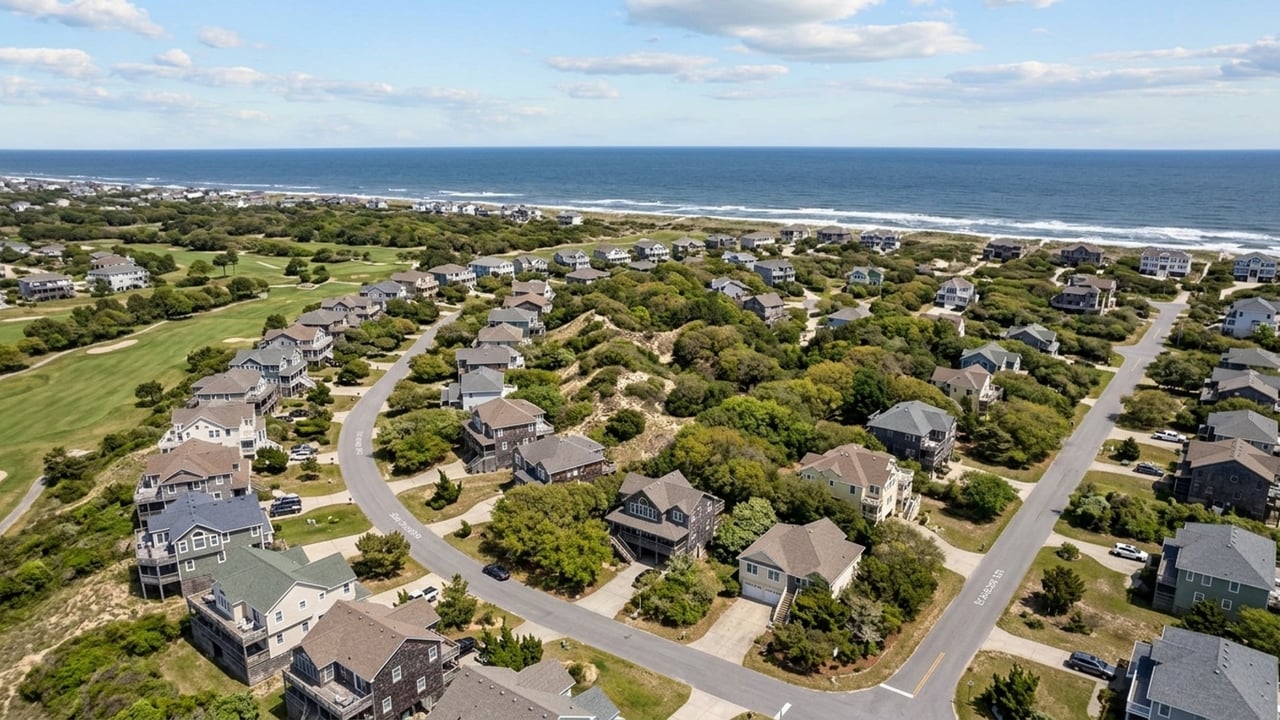
Corolla has never incorporated as a town. It's the name of a post office, not a municipality with a mayor or a town council. What buyers call "Corolla" is really a run of Currituck County oceanfront made up of separate planned communities and one distinct off-road zone, all sharing a single ZIP code, 27927, because everyone's mail routes through the same building.
The named communities include:
- Pine Island
- The Currituck Club
- Ocean Sands
- Whalehead
- Buck Island
- Monteray Shores
- Corolla Light
- Villages at Ocean Hill
Each of these operates under its own homeowners association, its own covenants, and in many cases its own private roads. North of where the pavement ends on NC-12, a separate 11-mile stretch of beach known as the 4x4 area, or Carova, functions as an entirely different kind of real estate market with different infrastructure, different financing rules, and different governance. All of it gets marketed and searched under one name.
That matters because when a portal or a market report gives you "Corolla's median price," it's blending gated golf communities, walkable historic-village lots, and unpaved beach cottages into a single figure. The number is real. It just isn't describing any one property you could actually buy.
The Same ZIP Code, Several Different Medians
You can see the fragmentation in the data itself. A snapshot of active listings pulled in mid-September 2026 put the ZIP code's median list price at $699,000 across 229 properties. Public MLS-sourced housing data covering the three months ending April 2026 showed a median sale price of $865,000, up 8.1% year over year, with 60 homes sold that April compared with 54 the year before. A separate market summary from earlier this year put the most recent monthly median sale price at $755,000, down roughly 3.5% from the year prior. Yet another roundup this year placed the number closer to $890,000, up 13% year over year.
Four sources, one ZIP code, four numbers that don't reconcile into a clean trend line. That isn't sloppy reporting. It's what happens when a $170,000 two-bedroom cottage with a well and septic tank, a $4.9 million oceanfront estate in a gated resort community, and everything between them all get counted as "Corolla" in the same month. Whichever slice of inventory happened to close pulls the median in a different direction. A buyer comparing "the Corolla number" against a number from Duck or Kitty Hawk is comparing a moving average of unlike things to a more internally consistent one.
The practical takeaway is that a median price for Corolla tells you almost nothing about what you can buy for that amount. You need to know which Corolla you're pricing before the number means anything.
What a Beach Drive Actually Buys and Costs
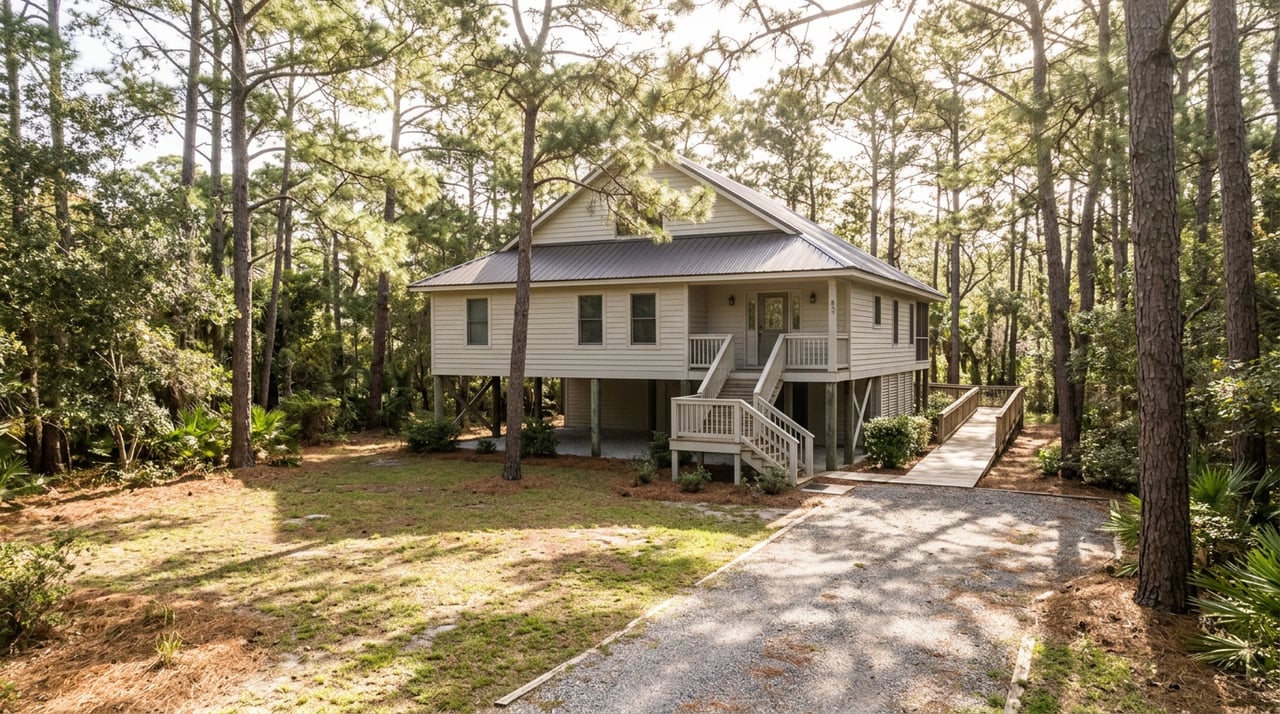
Carova is where the fragmentation shows up most sharply. The paved road ends at the north end of Corolla, and from there it's roughly 11 miles of beach driving to reach the community, through a corridor that passes Swan Beach and North Swan Beach before the state line. Every property up that stretch runs on a private well and a private septic system. There's no municipal trash pickup, no gas station, no grocery store, and a single volunteer fire and rescue department covers the roughly 600 homes spread across the entire corridor. Housing stock is limited to single-family detached homes, no trailers, duplexes, or condominiums.
Prices in Carova span a wider range than almost anywhere else on the Currituck Outer Banks. Smaller two- and three-bedroom cottages built in the 1970s through the 1990s can start near $170,000, while large oceanfront homes built for rental income, often eight to twelve bedrooms, run well above $900,000. One estimate placed the area's median listing price at $689,000 as of late 2025, sitting almost exactly between those two extremes.
The financing wrinkle is the part most buyers don't see coming until they're already under contract. Because Carova sits inside a federally designated CBRS unit, the Coastal Barrier Resources Act blocks NFIP flood insurance on construction built after 1982. Since most conventional, FHA, VA, and USDA loans require NFIP-eligible flood coverage in a mapped flood zone, that rule quietly filters the buyer pool down to cash purchasers and lenders willing to underwrite against private flood policies. It's not a defect in the market. It's a structural fact of buying land inside a federal coastal barrier designation, and it means the "Corolla" price you see for a Carova listing is being paid by a different kind of buyer than the one paying the "Corolla" price for a home in a paved, HOA-run community three miles south.
What HOA Dues Actually Buy You
South of the sand, inside the paved communities, the differences are about lifestyle infrastructure rather than financing eligibility. The Currituck Club, Corolla Light, and Monteray Shores each run active homeowners associations that maintain private roads, clubhouses, and recreational amenities. The Currituck Club's fitness center reopened in January 2026 with new equipment, part of the ongoing amenity investment that comes with dues in a resort-style HOA. Corolla Light runs its own sports center and trolley service to the beach. Monteray Shores maintains a soundfront pier, tennis courts, and a boat ramp for its residents.
Closer to the historic core, Whalehead and old Corolla Village trade some of that amenity infrastructure for walkable proximity to the Currituck Beach Lighthouse, the Whalehead Club, and the shops at TimBuck II. Neither approach is better. They're different products sold under the same town name, with dues structures, covenants, and amenity packages that a buyer needs to review individually rather than assume based on the word "Corolla" alone.
Who Approves the Next Project Next Door
Because none of these communities is an incorporated town, land use decisions run through the Currituck County Board of Commissioners rather than a local town council. That distinction became visible in a real dispute over a 13-acre mixed-use project proposed for the Monteray Shores subdivision, known as the Corolla Boat Club. County commissioners initially tabled the first phase over traffic concerns before approving it, and an amended sketch plan that reduced the project's open space by 1.45 acres cleared a quasi-judicial hearing in August 2023. Residents who'd bought into what they understood as a quiet planned community launched a petition opposing the added density, and it had gathered more than 1,150 signatures within months.
Whatever your view of that particular project, the mechanism is worth understanding before you buy. Residents of an HOA-run subdivision in unincorporated Currituck County don't have a town council they can vote onto or off of over land-use disputes. Zoning and special-use decisions for their community are made by the same county board that governs a much wider stretch of Currituck, alongside every other subdivision sharing the Corolla name. If a quiet cul-de-sac reputation matters to your purchase, it's worth reading the county's planning agenda for that community, not just the HOA's marketing material.
A Few Straight Answers
Is Carova technically part of Corolla? It shares the Corolla ZIP code and post office, but it functions as a separate market with different infrastructure, financing rules, and no paved-road access.
Can any Corolla property get a normal mortgage? Most can. The financing restriction described above applies specifically to post-1982 construction inside the Carova/4x4 area's federal coastal barrier designation, not to the paved planned communities south of the beach access ramp.
Does Corolla have its own local government? No. It's unincorporated, and land-use, zoning, and special-use decisions for every subdivision under the Corolla name go through the Currituck County Board of Commissioners.
If you're comparing a listing in Corolla Light against one in Whalehead, or weighing whether a Carova property's price makes sense once you account for financing, Cameron Griggs can walk through what each community's HOA documents, county planning history, and financing realities actually mean for your offer.